Zebit vs Katapult: Which BNPL Option Is Better?
For former Zebit customers, Katapult is the closest 1-for-1 replacement on the US market. Both target shoppers who cannot qualify for mainstream credit, both use soft-pull approvals, and both let you spread a purchase over several months. Here is a direct Zebit vs Katapult comparison.
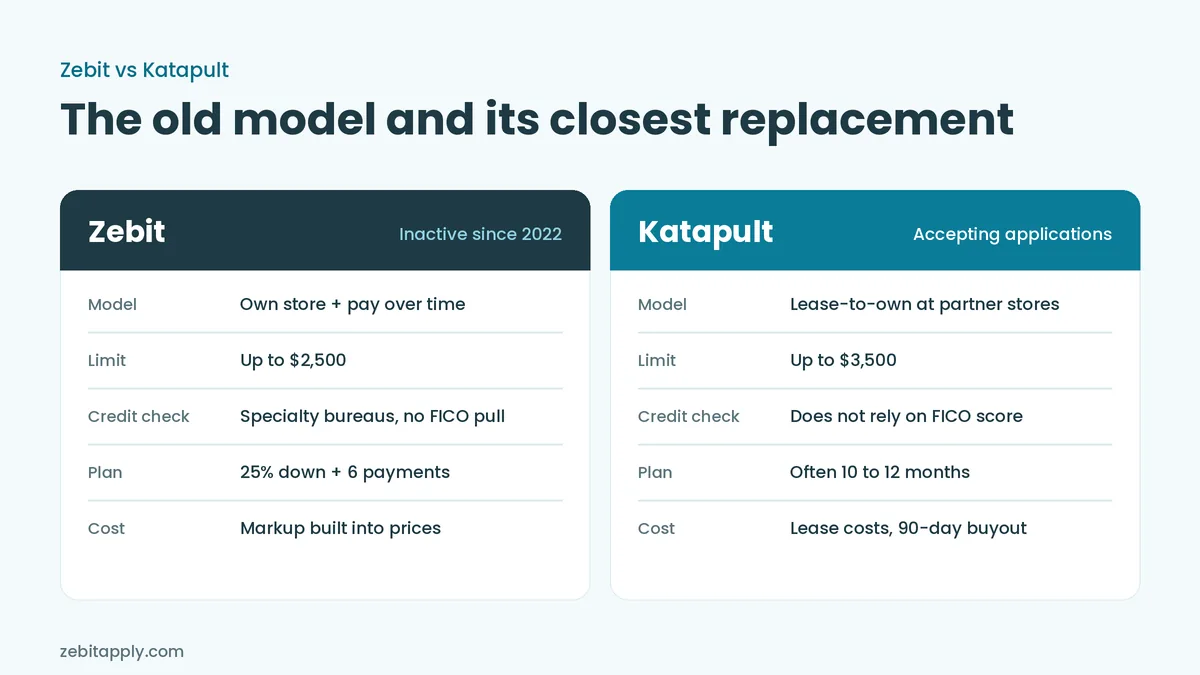
| Factor | Zebit (historical) | Katapult (2026) |
|---|---|---|
| Status | Inactive since 2022 | Active and accepting applications |
| Approval type | Soft specialty-bureau pull | Own approval model; does not rely on FICO score |
| Credit impact | None at application | None at application |
| Max amount | Up to $2,500 | Up to $3,500 |
| Payment term | 6 months, fixed | Often 10 to 12 months; 90-day early purchase option |
| Interest | 0 percent (markup built into price) | Lease fees apply; early purchase discount available |
| Retailer coverage | Zebit Market only | Hundreds of partner retailers |
| Product categories | Electronics, furniture, appliances, jewelry | Electronics, furniture, mattresses, appliances |
| Late fees | None documented | None, per Katapult |
| Builds credit | Not reported to major bureaus | Not reported to major bureaus |
Where Katapult beats Zebit
Katapult is active and accepting applications today. Zebit is not. For most practical purposes, that is the deciding factor. Beyond availability, Katapult offers broader retailer coverage because it integrates with hundreds of merchants rather than running its own closed marketplace. If the sofa or laptop you want is sold by a Katapult partner retailer, you can lease it there. Zebit could only sell what Zebit had sourced into its own catalog.
Katapult also tends to have transparent lease-to-own fees that can be reduced by paying off early. Zebit's markup was invisible — it was priced into the sticker, which made it harder to compare against mainstream retail.
Where Zebit beat Katapult
On paper, Zebit's 0 percent APR with no late fees was simpler to understand than lease-to-own math. If you held a Zebit purchase to the full six-month term, you knew exactly what you would pay. Katapult's total cost on a long lease can exceed Zebit's old marketplace markup, especially if you ride a lease to its full term.
Zebit's six-month term also matched most shoppers' pay cycles cleanly. Katapult's bi-weekly or monthly lease structure can feel less predictable until you have run through one full cycle.
Zebit vs Katapult: shopper scenarios
You need a $1,200 laptop today
Winner: Katapult. Zebit cannot process a new order. Katapult can approve a lease at a participating retailer in seconds, without relying on your FICO score.
You can clear the balance in 90 days
Winner: Katapult. The early purchase option on a lease generally results in less markup than Zebit's old marketplace prices would have carried over the same timeframe.
You want zero fees and a known term
Winner (historically): Zebit. Today this is a moot point because Zebit is offline. If zero stated fees are a hard requirement, consider Affirm's Pay in 4 or Pay in 2 options, which have no interest for the shortest terms.
How Katapult works, step by step
- Shop at a partner retailer and choose Katapult as the payment option at checkout.
- Complete a short application. Katapult's retailer listing describes 14 required fields and an approval decision in under five seconds. It uses its own approval model rather than FICO scores.
- Review the lease and your early purchase options, then confirm your paydays so payments line up with them.
- Make the initial payment and sign. Each new lease starts with its own initial payment and its own schedule.
What Katapult really costs
Katapult is a lease, so you do not own the item until you make every payment or use an early purchase option. Keeping a lease to the end of its term costs more than buying the item outright. The 90-day early purchase option is the cheapest way to own it, and Katapult states it does not charge late fees. You can also return leased items and stop future payments, owing only what is already due.
Zebit worked differently: no lease, but the cost was built into marketplace prices. Our payment calculator shows how that markup added up. Before you sign with Katapult, ask for two numbers in writing: the total of all lease payments and the 90-day purchase amount.
Who should choose Katapult
- Good fit: you need an item now, your credit is thin or damaged, and you can pay it off within 90 days.
- Good fit: the store you want already offers Katapult at checkout.
- Poor fit: you expect to need the full lease term to pay. Compare a loan with a disclosed APR first.
- Poor fit: you want something above Katapult's $3,500 approval limit.
Sources
- Katapult: BigCommerce app listing and App Store listing
- Katapult checkout steps: Secretlab Katapult page
Bottom line
Katapult is the correct answer for anyone comparing Zebit vs Katapult today. Zebit is not an active option. Katapult covers the same shopper segment, keeps the no-credit-check approval model, and expands retailer coverage well beyond Zebit's closed marketplace. For shoppers who want to see Katapult quotes alongside Snap Finance, Progressive Leasing, and Affirm, our Compare Offers page runs a single soft-pull submission across the full partner network.